What is Coast FIRE? The Ultimate Guide & Calculator
Your Guide to Coast FIRE: Work Less, Live More
Imagine reaching a point in your career where you no longer have to save for retirement. Not because you're a billionaire, but because you've already invested enough that compound interest will do all the heavy lifting for you. You can take a lower-stress job, pursue a passion project, or work part-time, all while your nest egg grows silently in the background, ready for your golden years.
This isn't a pipe dream; it's a powerful financial strategy known as Coast FIRE.
For many, the traditional FIRE (Financial Independence, Retire Early) movement feels like an all-or-nothing sprint, requiring extreme frugality and sky-high savings rates. Coast FIRE offers a more balanced, flexible approach. It's a marathon, not a sprint, focusing on front-loading your investments so you can ease off the gas pedal decades before your actual retirement date.
In this comprehensive guide, we'll break down everything you need to know about Coast FIRE. We'll explore what it is, how it differs from other FIRE strategies, and most importantly, how to calculate your unique Coast FIRE number.
What Exactly is Coast FIRE?
Coast FIRE is the point at which you have enough money in your retirement accounts that, without contributing another penny, your investments will grow to support your desired lifestyle by your traditional retirement age (e.g., 65).
Think of it like this: you've pushed a giant snowball to the top of a very long hill. Your job is done. Now, you just need to let it roll. The snowball (your investment portfolio) will gather more snow (compound interest) on its own and become a massive boulder by the time it reaches the bottom of the hill (your retirement).
Once you've reached your Coast FIRE number, you are officially "coasting." You still need to work to cover your current living expenses, but the immense pressure to save for the future is gone. Your financial focus shifts from accumulating wealth for retirement to simply funding your present life.
Coast FIRE vs. Other FIRE Movements
To understand Coast FIRE better, it helps to compare it to its popular siblings:
- Traditional FIRE: This involves saving aggressively (often 50%+ of your income) to accumulate 25 times your annual expenses, allowing you to retire completely, often in your 30s or 40s.
- Barista FIRE: A stepping stone where you have enough invested to cover most of your needs, but you work a low-stress, part-time job (like a barista) for benefits and spending money.
- Fat FIRE: The goal is to retire early with a lavish lifestyle, requiring a much larger nest egg than traditional FIRE.
Coast FIRE is unique because it uncouples the need to save for retirement from your current job. It's a milestone, not an exit. It's about creating freedom and options during your career, not just at the end of it.
The Key Ingredients for Your Coast FIRE Calculation
Calculating your Coast FIRE number isn't complicated, but it requires a few key pieces of information. Understanding these variables will empower you to tweak your plan and see how different choices impact your timeline.
Here are the essential inputs:
- Current Age: Your starting point. The younger you are, the more powerful compounding is.
- Target Retirement Age: The age you plan to stop working entirely (e.g., 65).
- Current Retirement Savings: The total amount you have invested for retirement right now across all accounts (401k, IRA, etc.).
- Desired Annual Spending in Retirement: How much you expect to live on per year once you fully retire, stated in today's dollars.
- Expected Annual Investment Return: A reasonable estimate of your portfolio's average annual growth rate. Historically, the stock market has returned around 10% annually, but a more conservative 7-8% is often used for planning.
- Expected Inflation Rate: The average rate at which the cost of living increases. A long-term average of 2-3% is a common assumption.
How to Calculate Your Coast FIRE Number (Step-by-Step)
Ready to find your number? You can do it manually with a few calculations or use a simple tool. Let's walk through the manual process first so you understand the mechanics behind the magic.
Let's use an example: Sarah is 30 years old and wants to fully retire at 65. She plans to spend $60,000 per year in retirement.
Step 1: Calculate Your Traditional FIRE Number
First, you need to know how much you'll need at retirement. The most common method is the "25x Rule," based on a 4% safe withdrawal rate.
Formula: Desired Annual Spending x 25 = FIRE Number
- Sarah's Example:
$60,000 x 25 = $1,500,000
So, Sarah needs $1.5 million in today's dollars to retire.
Step 2: Project Your FIRE Number into the Future
That $1.5 million needs to be adjusted for inflation to maintain its purchasing power by the time Sarah is 65. We need to calculate its future value.
Formula: Future Value = Present Value x (1 + Inflation Rate) ^ Number of Years
Let's assume a 3% inflation rate. Sarah has 35 years until retirement (65 - 30).
- Sarah's Example:
$1,500,000 x (1 + 0.03) ^ 35 = $4,223,716
Sarah will need approximately $4.22 million by age 65 to have the same purchasing power as $1.5 million today.
Step 3: Find the Present Value of Your Future Goal
Now for the final step. Your Coast FIRE number is the amount you need today that will grow into that future number without any more contributions. This is a present value calculation.
Formula: Present Value (Coast FIRE Number) = Future Value / (1 + Investment Return) ^ Number of Years
Let's assume a 7% average annual investment return.
- Sarah's Example:
$4,223,716 / (1 + 0.07) ^ 35 = $395,780
Sarah's Coast FIRE number is approximately $395,780. This means if she can get $395,780 into her retirement accounts by age 30, she theoretically never has to save for retirement again. She just needs to earn enough to cover her living expenses until she's 65.
The Easy Way: Use Our Coast FIRE Calculator
While understanding the math is valuable, doing it by hand is tedious and prone to errors. A dedicated calculator simplifies the entire process.
Our free Coast FIRE Calculator does all these calculations for you instantly. Simply enter your variables:
- Your Current Age
- Your Target Retirement Age
- Your Current Retirement Savings
- Your Desired Annual Retirement Spending
- Your Expected Investment Return & Inflation Rate
The tool will immediately tell you your Coast FIRE number and show you how close you are to reaching it. It's the simplest way to get a clear picture of your financial future.
The Pros and Cons of a Coast FIRE Strategy
Coast FIRE is a powerful concept, but it's not without its trade-offs. It's crucial to weigh the advantages and potential risks before committing to this path.
Advantages of Coast FIRE
- Ultimate Flexibility: It provides the freedom to change careers, start a business, travel, or work part-time without jeopardizing your long-term retirement.
- Reduces Burnout: By removing the pressure to maximize income for savings, it allows you to escape the "golden handcuffs" of a high-stress job you may not enjoy.
- More Attainable: For many, reaching a Coast FIRE number in their 30s or 40s is far more realistic than achieving full traditional FIRE.
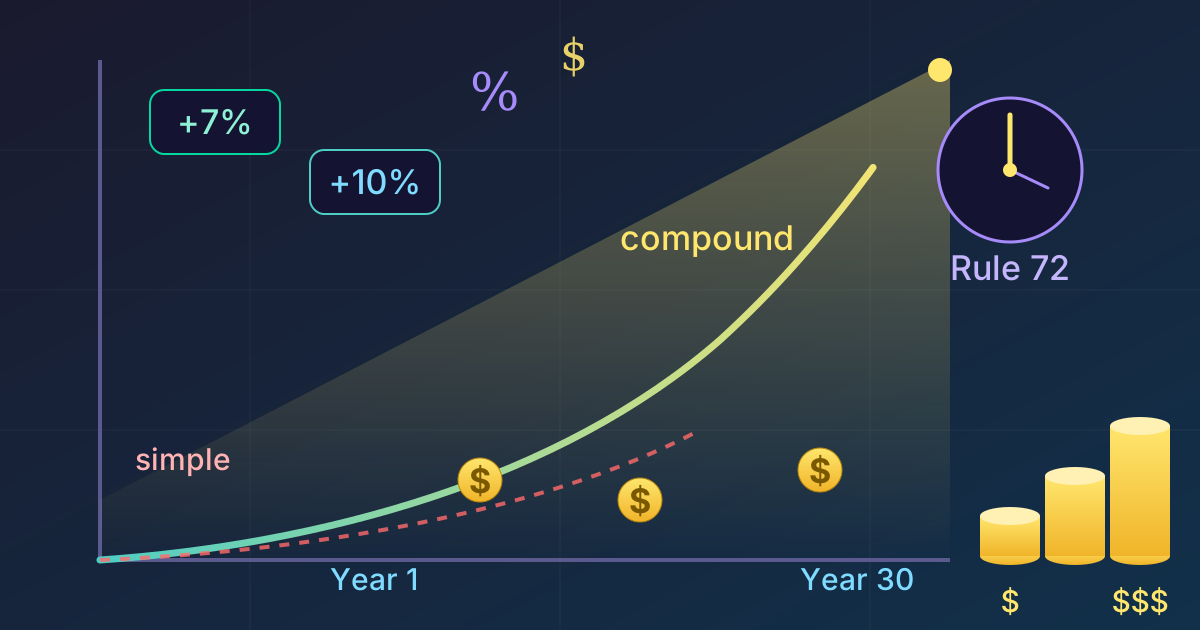
- Harnesses Compound Interest: It's a strategy built entirely on the magic of compounding over long periods, rewarding those who start investing early.
Disadvantages and Risks of Coast FIRE
- Market Risk: The plan relies on long-term average market returns. A sustained period of low returns could mean your nest egg falls short.
- Requires Discipline: Once you hit your number, you must resist the temptation to withdraw from your retirement accounts before your planned retirement age.
- Inflation Risk: If inflation runs significantly higher than your estimate for many years, the future value of your portfolio may be less than you need.
- Life Happens: The model doesn't account for major unexpected life events, like a catastrophic health issue, that could force you to tap into funds early.
Actionable Strategies to Reach Coast FIRE Faster
Inspired to reach your Coast FIRE number? Here are some practical strategies to accelerate your journey.
1. Front-Load Your Investments Aggressively
The earlier you invest, the harder your money works for you. In your 20s and early 30s, prioritize maxing out tax-advantaged accounts like your 401(k) and IRA. Every dollar you invest early is exponentially more valuable than a dollar invested a decade later.
2. Increase Your Income
While cutting expenses is effective, there's a limit to how much you can cut. Increasing your income has unlimited potential. Consider asking for a raise, switching to a higher-paying company, or starting a side hustle. If you're freelancing, be sure to plan for taxes. Using a tool like our Self-Employment Tax Calculator can help you understand your true earnings and budget effectively.
3. Minimize Your Biggest Expenses
For most people, the "big three" expenses are housing, transportation, and food. Finding creative ways to reduce these can supercharge your savings rate. One powerful strategy is house hacking—living in one unit of a multi-unit property you own while renting out the others. This can drastically reduce or even eliminate your housing costs. You can model different scenarios with our House Hacking Calculator to see if it's a viable path for you.
4. Keep Investment Fees Low
High fees are a silent killer of investment returns. A 1% management fee can consume nearly a third of your portfolio's potential value over several decades. Stick to low-cost, broadly diversified index funds or ETFs to ensure more of your money stays invested and working for you.
Conclusion: Start Your Journey to Financial Flexibility
Coast FIRE isn't about quitting work forever tomorrow. It's about strategically designing a life with more freedom, less stress, and greater control over your time. By front-loading your investment efforts, you give yourself the incredible gift of choice later in life.
You can choose to leave a toxic work environment, pursue a creative passion, or simply work less and spend more time with family—all with the peace of mind that your retirement is secure.
The first step is knowledge. Understanding your numbers transforms a vague dream into an actionable goal.
Ready to see what your future could look like? Take five minutes to plug your numbers into our free, privacy-focused Coast FIRE Calculator. Your journey to financial freedom starts now.