Your Guide to 2026 HSA Contribution Limits
Rising healthcare costs are a persistent concern for individuals and families across the country. A Health Savings Account (HSA) is one of the most powerful financial tools available for dealing with them, offering a unique triple-tax advantage for managing medical expenses and even saving for retirement. As savvy planners, we keep tabs on the official numbers, and the IRS has now answered the question on many people's minds: the 2026 HSA contribution limits are $4,400 for self-only coverage and $8,750 for family coverage.
The IRS released the official numbers in the second quarter of 2025 in Rev. Proc. 2025-19, and this guide has been updated with them. It will break down what an HSA is, review historical trends, walk through the official 2026 limits, and explore strategies to maximize this incredible account.
Try Full Moon Calendar 2026: free, no sign-up.
Update (official figures): The IRS released the official 2026 HSA limits in the second quarter of 2025 in Rev. Proc. 2025-19: $4,400 for self-only coverage, $8,750 for family coverage, and the $1,000 catch-up contribution unchanged. This article has been updated to replace the original projections with these confirmed figures.
What is a Health Savings Account (HSA)?
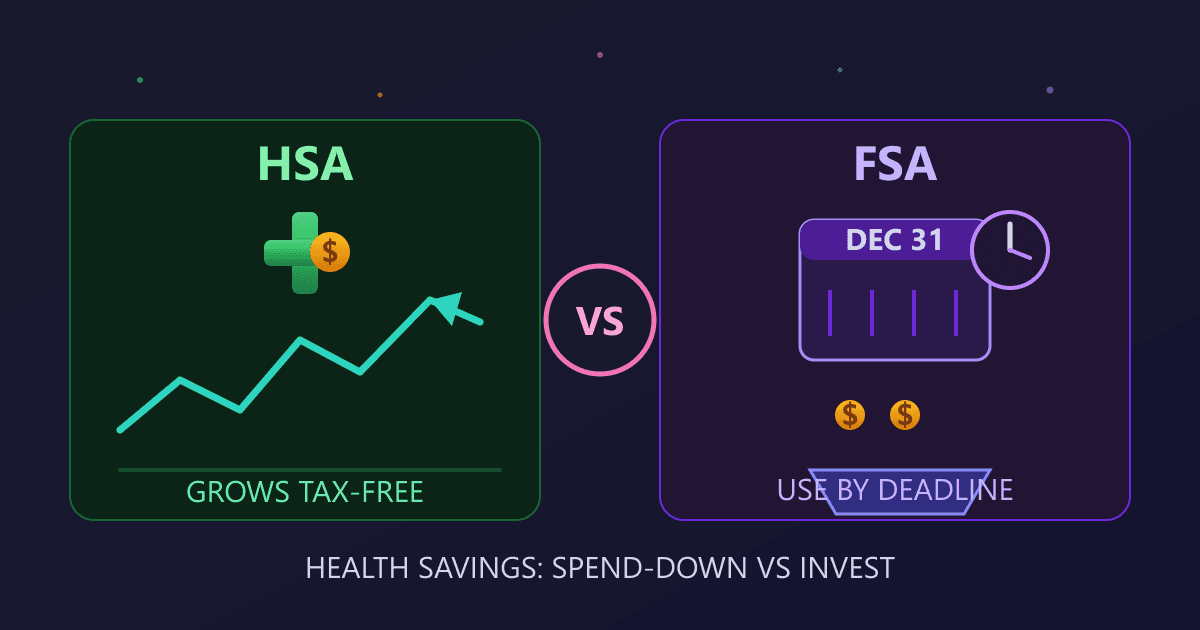
An HSA is a tax-advantaged savings account available to individuals enrolled in a High-Deductible Health Plan (HDHP). Think of it as a personal savings account, but specifically for qualified medical expenses. The funds you contribute are yours to keep, and they roll over year after year without expiring. This makes it fundamentally different from a Flexible Spending Account (FSA).
The Unbeatable Triple-Tax Advantage
The power of the HSA lies in its unique tax treatment, often called the triple-tax advantage:
- Tax-Deductible Contributions: The money you put into your HSA is tax-deductible (or pre-tax if done via payroll), reducing your current taxable income.
- Tax-Free Growth: The funds in your HSA can be invested and grow completely tax-free.
- Tax-Free Withdrawals: You can withdraw money at any time to pay for qualified medical expenses without paying any taxes.
This combination is unmatched by any other retirement or savings vehicle, including a 401(k) or a Roth IRA.
Who is Eligible for an HSA?
To contribute to an HSA, you must meet a few specific IRS requirements. The primary requirement is that you must be covered under a qualifying High-Deductible Health Plan (HDHP) on the first day of the month.
Additionally:
- You cannot be covered by any other non-HDHP health plan (with some exceptions for dental, vision, etc.).
- You cannot be enrolled in Medicare.
- You cannot be claimed as a dependent on someone else's tax return.
Understanding HDHP Requirements
The IRS defines what qualifies as an HDHP each year, setting minimum deductibles and maximum out-of-pocket spending limits. Here's a look at the official numbers for 2024, 2025, and 2026.
| Year | Plan Type | Minimum Deductible | Maximum Out-of-Pocket |
|---|---|---|---|
| 2024 | Self-Only | $1,600 | $8,050 |
| Family | $3,200 | $16,100 | |
| 2025 | Self-Only | $1,650 | $8,300 |
| Family | $3,300 | $16,600 | |
| 2026 | Self-Only | $1,700 | $8,500 |
| Family | $3,400 | $17,000 |
Your health plan must meet these criteria to be HSA-eligible.
HSA Contribution Limits: Past and Present
The amount you can contribute to an HSA is adjusted for inflation annually. Watching the trends helps us forecast what's to come.
Historical HSA Contribution Limits
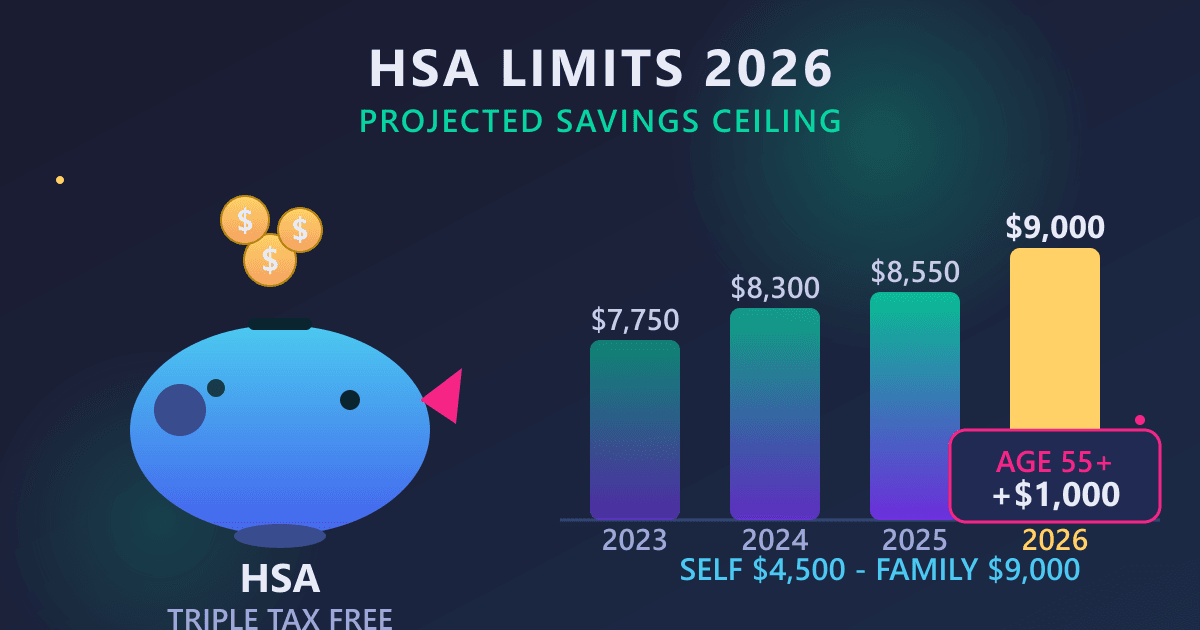
| Year | Self-Only Coverage | Family Coverage | Catch-Up Contribution (Age 55+) |
|---|---|---|---|
| 2023 | $3,850 | $7,750 | $1,000 |
| 2024 | $4,150 | $8,300 | $1,000 |
| 2025 | $4,300 | $8,550 | $1,000 |
As you can see, the limits have seen significant jumps in recent years due to higher inflation.
The Official 2026 HSA Contribution Limits
So, what did the IRS settle on for 2026? The agency uses the Consumer Price Index for All Urban Consumers (CPI-U) from a specific 12-month period (typically ending in March) to calculate the next year's adjustments. The results are then rounded down to the nearest $50.
Given the persistent, albeit moderating, inflation, 2026 brought another increase, announced in Rev. Proc. 2025-19.
Official 2026 HSA Contribution Limits (IRS Rev. Proc. 2025-19):
| Contribution Type | 2025 Limit | 2026 Official Limit | Increase |
|---|---|---|---|
| Self-Only Coverage | $4,300 | $4,400 | +$100 |
| Family Coverage | $8,550 | $8,750 | +$200 |
| Catch-Up Contribution | $1,000 | $1,000 | $0 |
Notes on the Official 2026 Numbers:
- Self-Only: The limit rose from $4,300 to $4,400, a 2.3% increase and a smaller jump than the previous two years.
- Family: The family limit rose from $8,550 to $8,750 (also about 2.3%), just $50 shy of double the self-only limit.
- Catch-Up Contribution: The $1,000 catch-up contribution for those age 55 and older is fixed by statute and does not adjust for inflation. It remains $1,000.
These increases allow individuals and families to shelter even more of their income from taxes while building a solid fund for healthcare needs.
The HSA as a Supercharged Retirement Account
Many financial experts consider the HSA the ultimate retirement investment vehicle, even better than a 401(k) or IRA. Why? Because of its triple-tax advantage and flexibility.
Here's the advanced strategy: If your budget allows, pay for your current medical expenses out-of-pocket instead of using your HSA funds. This allows the money inside your HSA to remain invested and grow tax-free for decades. You can then reimburse yourself for all those past medical expenses tax-free at any point in the future, even deep into retirement.
Imagine contributing the maximum to your family HSA for 30 years. With the limits rising, you could easily accumulate over $500,000, and with modest investment returns, that balance could grow to well over $1 million.
This long-term strategy is a cornerstone of many financial independence plans. By building a powerful tax-advantaged account like an HSA, you can significantly shorten your path to financial freedom, a concept you can explore further with our Coast FIRE Calculator.
After age 65, the HSA becomes even more flexible. You can still withdraw funds tax-free for medical expenses. But you can also take distributions for any other reason (like travel, home repairs, or just living expenses) and pay only ordinary income tax, just like a traditional 401(k) or IRA. The 20% penalty for non-medical withdrawals disappears.
HSAs for Freelancers and the Self-Employed
For those who are self-employed, an HSA is an absolute must-have. Not only do you get the same triple-tax advantage, but the benefits are amplified.
When you contribute to an HSA as a self-employed individual, you take the deduction directly on your Form 1040 as an “above-the-line” deduction. This lowers your adjusted gross income (AGI), which is the basis for calculating many other taxes and credits. A lower AGI can lead to a lower overall tax bill, including your self-employment taxes.
Managing your finances as a freelancer involves understanding your total tax picture. An HSA contribution is a powerful tool to reduce your tax liability. To see how this fits into your overall financial obligations, use our handy Self-Employment Tax Calculator to get a clearer view of your responsibilities.
Frequently Asked Questions (FAQs) About HSAs
What happens to my HSA if I switch to a non-HDHP plan?
You can no longer contribute to your HSA, but the account is still yours. You can use the existing funds for qualified medical expenses tax-free, and you can continue to let the balance grow through investments. You own the account outright.
Can I use my HSA for non-medical expenses?
Yes, but it comes with a cost. If you are under age 65, withdrawals for non-qualified expenses are subject to both ordinary income tax and a 20% penalty. After age 65, the 20% penalty is waived, and it functions like a traditional retirement account where you only pay income tax on the withdrawal.
Can my employer contribute to my HSA?
Yes! Many employers offer contributions to employee HSAs as part of their benefits package. These contributions are not taxable to you and count toward your annual contribution limit. For example, with the 2026 family limit of $8,750, if your employer contributes $1,000, you can contribute up to $7,750 yourself.
What are some examples of qualified medical expenses?
Qualified medical expenses are broadly defined by the IRS in Publication 502. They include costs for:
- Doctor visits and co-pays
- Prescription drugs
- Dental and vision care (including glasses and contacts)
- Chiropractic care
- Medical equipment and supplies
- Medicare premiums in retirement
Conclusion: Start Planning for 2026 Today
A Health Savings Account is a uniquely powerful tool for managing healthcare costs and building long-term wealth. By understanding the rules and planning ahead, you can get the most out of it. The official 2026 HSA contribution limits ($4,400 for self-only coverage and $8,750 for family coverage) bring another healthy increase, allowing you to save even more on a tax-advantaged basis.
Whether you're using it for current medical bills or as a stealth retirement account, maximizing your HSA contributions is one of the smartest financial moves you can make. Start planning now to take full advantage of the limits in the years to come.
Ready to explore more ways to optimize your finances? Check out the wide array of free financial tools and calculators available here at Practical Web Tools.